Understanding How Repossession Works
Credit repair is fundamentally about managing three factors: accuracy of reports, payment behavior going forward, and aging of negative items. You can't change history, but you can correct inaccuracies, prove you're financially responsible now, and let time fade old damage. Most people dramatically underestimate what's possible because they think accurate negative information is permanent (it fades in power over time).
Start by checking your reports (free at AnnualCreditReport.com), identifying errors, and disputing inaccuracies in writing. While disputes process, focus on new credit behavior: pay every bill on time, reduce existing balances, avoid new hard inquiries. This dual approach of fixing reports while building positive history compounds over months.
An authorized-user account may help or hurt your credit, depending on the reported balance and payment history. Ask the issuer whether it reports authorized users. There is no guaranteed point increase or timing. See FICO’s explanation of authorized-user accounts.
If payments are overdue, contact the creditor to discuss affordable options. Making future payments on time can help build a better payment history, but it does not erase past late payments. Score changes depend on your full credit report and the scoring model.
Your Rights During a Repossession in Texas
Texas economy is diverse: oil and gas, tech, agriculture, manufacturing. Economic downturns in any sector hit credit scores of affected workers. 2015 energy crash, 2020 pandemic shutdowns, and regular business cycles all create credit casualties. What matters is recovery, and Texas law gives you tools to recover.
Texas generally protects current wages from garnishment for ordinary consumer debts. Exceptions apply to certain obligations, including support, taxes and some student loans. Bank-account collection follows different rules. See the Texas State Law Library’s debt-collection guide and get legal advice for your situation.
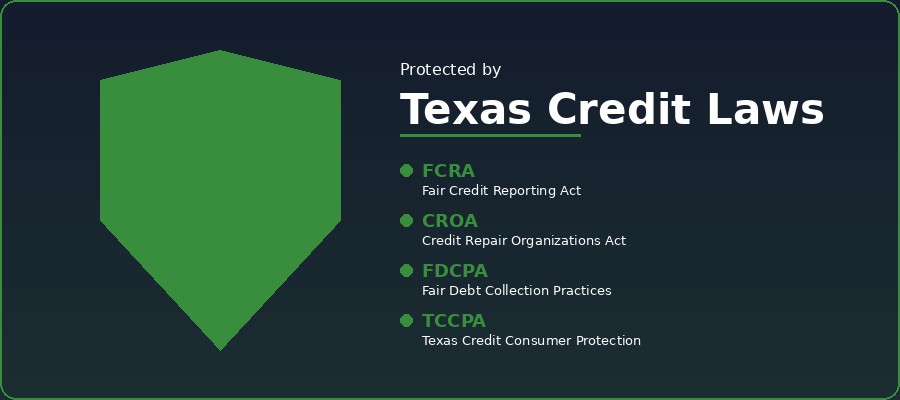
Credit repair in Texas involves knowing both federal law (FCRA, FDCPA, CROA) and Texas-specific rules (TCSOA, wage garnishment limits, homestead exemptions). A good Texas credit professional understands both and uses both to build the best strategy for your situation. DIY is possible but having local expertise helps.
Whether you're in San Antonio, Dallas, Houston, Austin, or a smaller Texas city, credit repair principles are the same: fix reports, build positive history, and let time heal. The details vary — Austin's tech economy is different from Houston's energy sector — but the core strategies work statewide. Reach out to 755CreditScore at 832-696-0755 for a free consultation.
The Credit Score Impact of a Repo
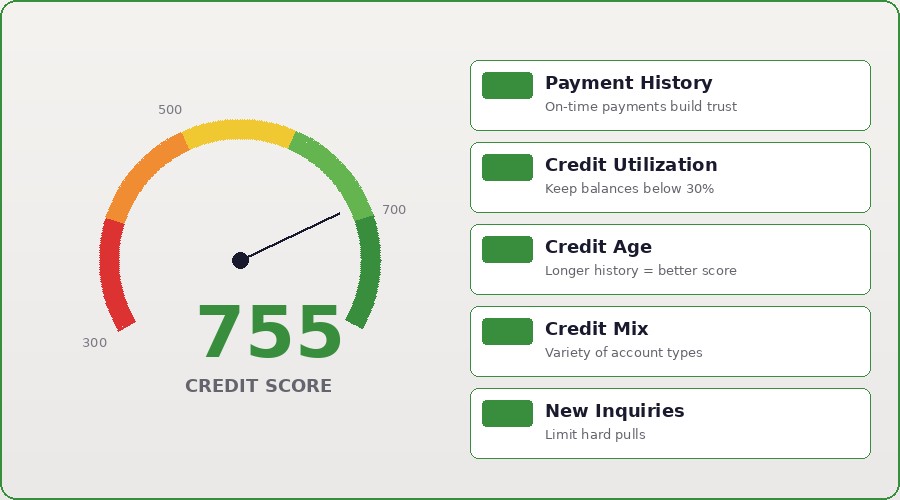
Good credit repair isn't a single move — it's a comprehensive approach combining multiple strategies simultaneously. Check your reports for errors (dispute inaccuracies), reduce balances (payment history and utilization), become an authorized user on positive accounts (mix and age), stay current on all new payments (the most important factor), and wait for negative items to age (time heals credit wounds).
Credit-report updates and score changes take different amounts of time. A corrected error or lower reported balance may affect a score after the bureau receives the update. No particular score increase or completion date is guaranteed.
You can dispute inaccurate, incomplete, duplicated or outdated information for free. Accurate, current negative information generally cannot be removed simply because it hurts your score. See the CFPB’s explanation of credit-report corrections.
You may choose professional help with reviewing reports and organizing disputes, but you can dispute errors yourself for free. Before hiring a provider, compare its written services, fees and cancellation terms. Avoid promises of guaranteed removals or score increases.